International health insurance can help pay for medical care while you live, work, study, or spend extended periods abroad. The right plan depends on where you will live, how long you will stay, which medical services you need, and whether you want coverage for treatment in the United States.
Choosing a policy requires more than comparing monthly premiums. Annual benefit limits, deductibles, exclusions, prescription benefits, medical evacuation, and pre-existing condition rules can significantly affect the protection you receive.
For U.S. citizens and residents planning an international move, the goal is to find coverage that fits their circumstances without paying for benefits they do not need or overlooking expenses they may have to cover themselves.
What Is International Health Insurance?
International health insurance, sometimes called international private medical insurance, is designed to provide medical coverage across one or more countries, often for people living abroad or spending extended periods outside their home country.
Depending on the policy, benefits may include:
- Inpatient hospital care and surgery
- Outpatient appointments and specialist consultations
- Diagnostic tests and medical imaging
- Prescription medications
- Emergency medical treatment
- Maternity care and mental health services
- Medical evacuation and repatriation benefits
Not every plan includes all these benefits. Some policies cover hospital treatment but exclude routine outpatient care unless you purchase additional coverage.
International health insurance may suit expatriates, families relocating overseas, retirees, international students, and remote workers whose lives involve more than occasional travel.
Before comparing policies, determine whether you need ongoing medical coverage while living abroad or protection primarily for unexpected medical emergencies during a trip.
International Health Insurance vs. Travel Insurance
International health insurance and travel insurance serve different purposes, although their benefits can overlap.
International health insurance generally focuses on medical care during an extended stay or while living abroad. Travel insurance typically focuses on problems associated with a trip, such as cancellation, interruption, lost baggage, and certain unexpected medical expenses.
Travel medical insurance may be available separately or as part of a broader travel insurance package. The exact benefits depend on the policy.
| Feature | International Health Insurance | Travel Insurance with Medical Benefits |
| Main purpose | Medical coverage while living abroad or staying internationally for an extended period | Protection against covered problems during a trip |
| Routine medical care | May be available, depending on the plan | Often limited or unavailable |
| Hospital treatment | Commonly included, subject to policy terms | Often focuses on eligible emergencies |
| Prescription medications | May be covered under specified benefits | Depends on the medical coverage and policy conditions |
| Trip cancellation | Usually not the main purpose | May be included |
| Medical evacuation | May be included or offered as an option | May be included, depending on the policy |
| Coverage duration | Depends on eligibility, contract, and renewal provisions | Depends on the trip dates and policy conditions |
Neither category is automatically better for every traveler.
A person taking a two-week vacation may primarily need travel medical coverage. Someone relocating overseas for a job may need benefits for regular appointments, ongoing prescriptions, and hospital care throughout a longer stay.
A longer trip does not automatically mean that a particular international policy is appropriate. Eligibility and coverage depend on the insurer’s rules, your destination, and the terms of the contract.
For a closer look at short-trip protection, read our guide to Comprehensive travel insurance coverage.
How to Choose International Health Insurance
The most useful approach is to assess your needs before requesting quotes. This helps you compare similar benefits rather than choosing a policy based on price alone.
1. Confirm Where You Need Coverage
Start by listing every country where you expect to live, work, study, or spend substantial time.
Some policies cover a defined region, while others offer broader geographical coverage. Certain plans also treat the United States differently from other countries.
Check whether the policy covers:
- Your primary country of residence
- Other countries you expect to visit regularly
- Temporary trips back to the United States
- Planned treatment outside your country of residence
- Emergency care while traveling in countries outside your main coverage area
Do not assume that worldwide coverage automatically means every country, hospital, treatment, or expense is covered.
If you plan to move between countries, confirm the insurer’s notification requirements and whether a change in residence affects eligibility, premiums, or benefits.
2. Decide Which Medical Services Matter Most
The next step is to decide whether you need hospital-only coverage or broader protection for routine healthcare.
Inpatient coverage generally applies to eligible treatment that requires hospital admission. Depending on the plan, it may cover surgery, hospital accommodation, and other approved hospital services.
Outpatient coverage can apply to eligible consultations, diagnostic tests, specialist appointments, and other treatment that does not require an overnight hospital stay.
Prescription drugs, maternity care, mental health treatment, dental care, and preventive services may have separate conditions or optional benefits.
Consider your everyday needs. Someone who rarely visits a doctor may prioritize substantial hospital coverage and emergency benefits. A family with children may place greater value on routine consultations, specialist access, and prescription coverage.
The important distinction is that a plan with more benefits is not necessarily the best fit if it raises the premium for services you are unlikely to use.
3. Compare Annual Benefit Limits
An annual benefit limit is the maximum amount a policy may pay for covered expenses within a specified period. Some benefits also have their own sublimits.
When reviewing a policy, check:
- The overall annual maximum
- Limits for hospital treatment and particular services
- Separate limits for outpatient care and prescriptions
- Whether evacuation expenses have a separate maximum
- Whether any benefits are subject to per-visit or annual caps
A high overall maximum does not guarantee generous coverage for every treatment. A plan can advertise a substantial annual limit but still restrict particular services through sublimits, exclusions, or other conditions.
Compare the actual benefit schedule rather than relying only on a headline figure.
4. Calculate the Deductible and Other Out-of-Pocket Costs
The premium is only one part of the cost of international health insurance.
A deductible is the amount you must pay toward eligible expenses before the insurer begins paying according to the policy’s terms.
Coinsurance is the portion of a covered expense you remain responsible for after the applicable deductible or other requirements have been satisfied. A policy may also require fixed copayments for certain services.
For example, consider two hypothetical plans:
- Plan A: A lower annual premium but a higher deductible.
- Plan B: A higher annual premium but a lower deductible.
Plan A may cost less if you make few claims. Plan B may offer more predictable costs when you use covered medical services.
These are illustrative trade-offs, not a prediction of which plan will be cheaper for you. The outcome depends on the benefit design, eligible expenses, and your medical needs.
When comparing quotes, look at both the annual premium and the amount you could reasonably have to pay yourself.
5. Review Pre-Existing Condition Rules
A pre-existing condition is a health condition that existed before coverage began, as defined by the relevant policy.
International health insurance policies differ in how they handle pre-existing conditions. Depending on the insurer and contract, a condition may be excluded, accepted with restrictions, covered under specified terms, or subject to additional underwriting.
Before applying, find out:
- Whether a medical questionnaire is required
- Which conditions must be disclosed
- Whether medical records or additional information may be requested
- Whether specific conditions will be excluded
- Whether waiting periods or special limitations apply
- Whether the final offer differs from the initial quote
Answer medical questions accurately and review the insurer’s written decision. Do not assume a condition is covered simply because the application was accepted.
If you have an ongoing health condition, ask for written clarification about the treatment, medication, and follow-up care that would be eligible under the proposed policy.
Our guide to Travel insurance with pre-existing medical conditions explains why medical history and policy wording also matter when arranging shorter-trip coverage.
6. Check Medical Evacuation and Repatriation Benefits
Medical evacuation and repatriation are different benefits.
Medical evacuation generally refers to medically necessary transportation to an appropriate facility when suitable treatment is unavailable locally, subject to the policy’s conditions.
Repatriation can refer to medically arranged transportation back to your home country or, in some policies, arrangements following death abroad. The precise meaning and eligibility conditions depend on the contract.
When reviewing these benefits, check:
- What circumstances trigger coverage
- Whether the insurer must authorize the transportation
- Who decides whether evacuation is medically necessary
- Which destinations or facilities are eligible
- Whether the benefit has a separate financial limit
- Whether an accompanying person or return journey is covered
Do not assume that evacuation means you can request transportation to any hospital you prefer. Insurers may apply medical necessity, assistance, and authorization requirements.
7. Understand Provider Networks and Claims
A plan’s payment arrangements can affect how easily you access treatment abroad.
Some insurers have arrangements with participating hospitals or providers that may allow direct billing for eligible services. In other situations, you may have to pay the medical provider first and submit a claim for reimbursement.
Neither arrangement guarantees that every expense will be covered.
Before choosing a plan, ask whether:
- Hospitals and specialists in your destination are accessible under the policy
- Direct billing is available in the locations you expect to use
- You need approval before planned admissions or expensive procedures
- Emergency treatment must be reported within a specified period
- Claims require itemized bills, medical reports, or translations
- The policy sets deadlines for submitting claims
Keep copies of invoices, medical records, prescriptions, and communications with the insurer.
For planned treatment, request confirmation of coverage and any required preauthorization before proceeding. For an emergency, follow the insurer’s emergency assistance instructions when circumstances permit.
8. Check Eligibility, Waiting Periods, and Renewal Terms
A plan that appears suitable may not be available to every applicant.
Insurers can apply eligibility rules relating to age, residence, destination, medical history, and other underwriting factors. Waiting periods may also apply to particular benefits.
If you are planning to remain abroad for several years, examine the policy’s renewal provisions carefully.
Ask whether renewal is guaranteed under specified conditions, whether premiums can change, and whether age or residence changes affect future coverage. Do not assume that renewal works the same way across all international health insurance products.
Families should also verify dependent eligibility, maternity benefits, children’s coverage, and how premiums change when adding family members.
Retirees should pay particular attention to eligibility, medication coverage, access to ongoing care, and the insurer’s rules for maintaining coverage as circumstances change.
What Does International Health Insurance Cost?
The cost of international health insurance varies by applicant and policy. There is no single monthly premium that accurately represents what every American living abroad will pay.
Important pricing factors include:
- Age: The insurer’s age-rating and eligibility rules affect the quote.
- Country or region: The area where you want coverage can affect pricing.
- U.S. coverage: Including treatment in the United States may change the cost significantly.
- Deductible: Choosing a higher deductible may reduce the premium while increasing your potential out-of-pocket costs.
- Benefit level: Broader inpatient, outpatient, and additional benefits can affect pricing.
- Medical underwriting: Medical history and the insurer’s underwriting approach may affect the offer.
- Family composition: Covering a spouse or dependents changes the overall quote.
When researching international health insurance cost per month, compare quotes that use similar assumptions. One quote might cover hospitalization only, while another includes outpatient visits, prescriptions, and other services. Comparing their premiums without accounting for these differences can be misleading.
Ask for a written quote that explains the premium, deductible, benefit limits, exclusions, and any applicable waiting periods.
Also ask whether the quote is guaranteed for a defined period and what could cause the price to change at renewal.
For consumers comparing international health insurance plans, the most useful question is not simply which quote is cheapest. It is which policy offers the necessary protection at a cost that fits the budget.
Does U.S. Health Insurance Cover You Abroad?
You should not assume that your current U.S. health insurance will pay for healthcare in another country.
Coverage depends on the specific policy, provider network, employer arrangement, and circumstances of treatment. Confirm international benefits directly with your insurer before leaving the United States.
Medicare has particularly important limitations. Medicare.gov explains that Original Medicare generally does not cover medical care outside the United States, although limited exceptions exist. Some Medigap policies may cover certain emergency medical expenses abroad, subject to their terms. Medicare Advantage plans can also have limited foreign emergency benefits, depending on the plan.
Read the official Medicare guidance on coverage outside the United States before making arrangements.
The U.S. Department of State also recommends reviewing insurance before traveling and notes that U.S. health insurance, including Medicare and Medicaid, usually does not cover care abroad. Its International Traveler’s Checklist explains why travelers should assess their medical coverage and possible evacuation needs.
If you plan to return to the United States for routine treatment, check whether your international policy covers care here, whether it is limited to emergencies, or whether the United States is excluded from the geographical coverage area.
Do You Need International Health Insurance for a Visa?
Some destinations and visa categories require applicants to provide evidence of qualifying health insurance. Others have different requirements depending on the visa, length of stay, employment status, or residency arrangement.
A policy that offers broad international coverage may not automatically satisfy a visa requirement.
Before purchasing, check the official immigration guidance or consular information for your destination. Confirm any specified coverage amounts, eligible policy types, required dates, and documentation rules.
The U.S. Department of State’s International Traveler’s Checklist recommends checking destination-specific entry and visa requirements. However, the destination country’s official authorities determine which insurance documents it accepts.
Obtain written confirmation that the proposed policy meets the relevant requirements before relying on it for a visa application.
Common Mistakes to Avoid When Choosing a Plan
A careful comparison can help prevent gaps in coverage and unexpected expenses.
Choosing on price alone. A low premium may come with a high deductible, narrow benefits, or exclusions that do not fit your needs.
Assuming every country is covered. Check the geographical coverage wording, including the rules for temporary visits to the United States.
Overlooking preauthorization. Some treatments require advance approval. Understand the procedure before arranging planned care.
Assuming a medical condition is covered. Review underwriting decisions, exclusions, and any condition-specific limitations in writing.
Ignoring the claims process. Find out how to contact the insurer, when to seek authorization, and what documents are required for reimbursement.
Treating travel and international health policies as interchangeable. Decide whether you need ongoing healthcare benefits, short-trip emergency coverage, or a combination of appropriate policies.
Failing to check renewal rules. If you expect to live abroad for years, understand the contract’s renewal terms before enrolling.
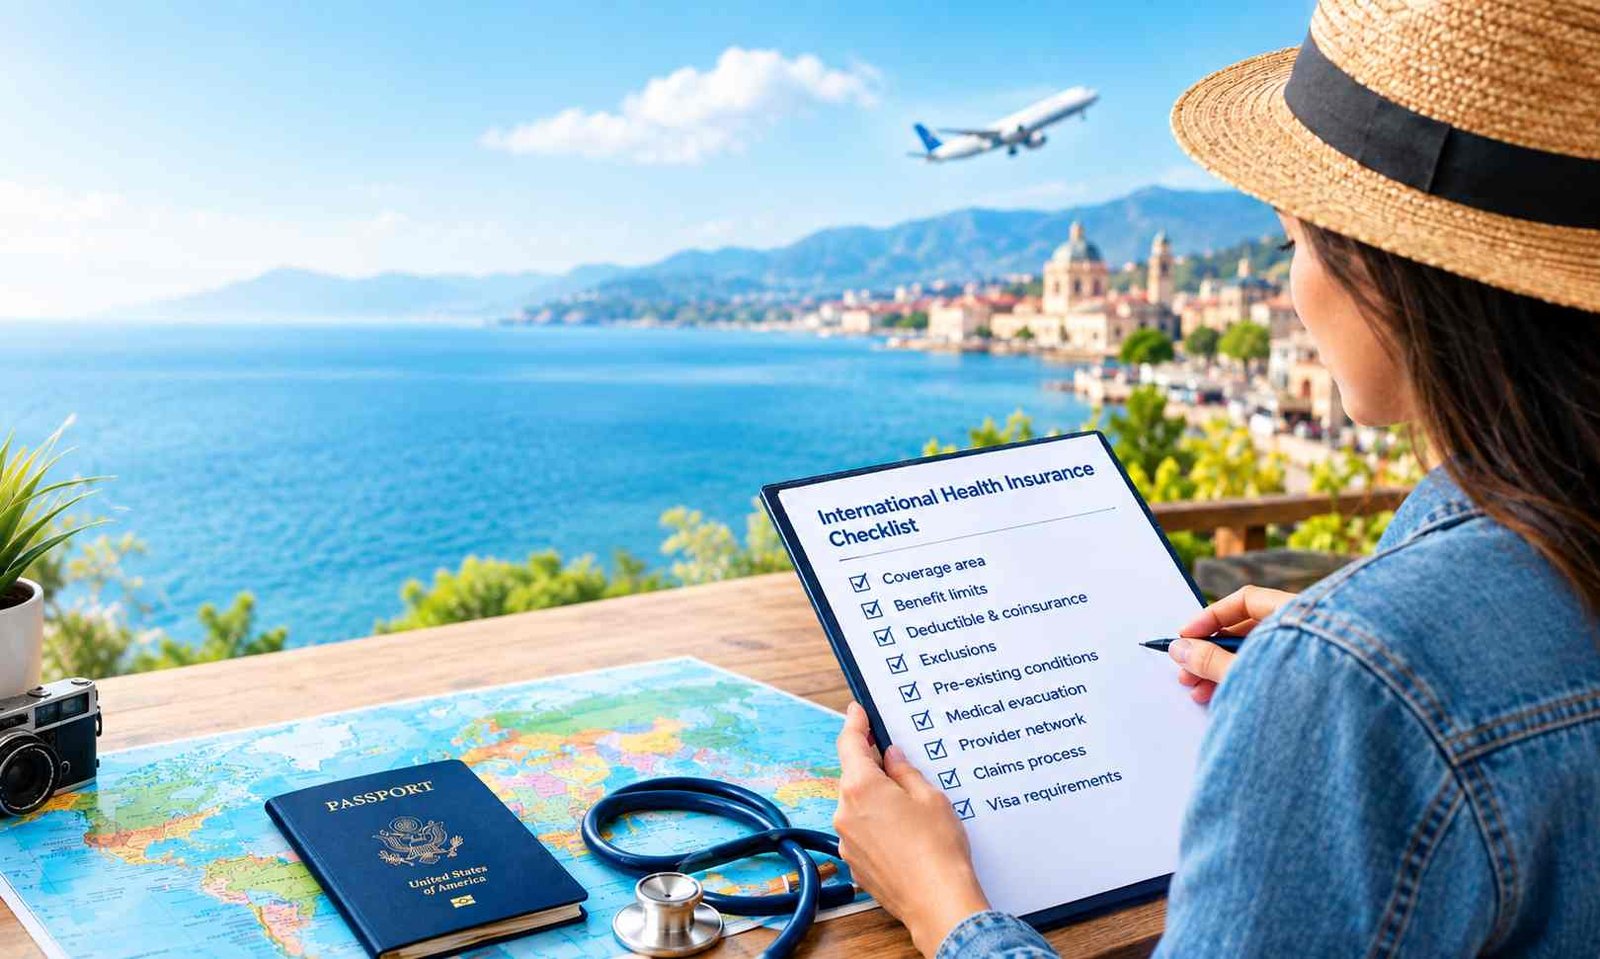
International Health Insurance Comparison Checklist
Before choosing a policy, use this checklist to compare the terms of each quote.
- Does the geographical coverage include every country where I expect to live or receive treatment?
- Is treatment in the United States included, excluded, or restricted?
- What are the annual maximum benefit and important sublimits?
- Are inpatient and outpatient services covered at the levels I need?
- What deductible, coinsurance, and other out-of-pocket costs apply?
- How are pre-existing conditions handled?
- Are prescription drugs, maternity care, and mental health benefits included where needed?
- What are the medical evacuation and repatriation provisions?
- Do I need to use a provider network or obtain preauthorization?
- How does direct billing work, and what happens when I pay a provider myself?
- Are there waiting periods, age restrictions, or eligibility conditions?
- What happens at renewal or if I move to another country?
- Does the policy meet any relevant visa or residency requirements?
Keep the insurer’s written answers with the policy documents. If a benefit is important to your decision, do not rely solely on a summary or verbal assurance.
Final Thoughts: Choose Coverage That Fits Your Life Abroad
The right international health insurance plan depends on where you will live, the care you need, your budget, and the risks you are prepared to pay for yourself.
Start by confirming your geographical coverage and eligibility. Then compare benefits, exclusions, deductibles, medical underwriting, evacuation provisions, and claims arrangements. If you plan to return to the United States or move between countries, verify those situations explicitly rather than assuming the policy covers them.
Before applying, compare complete policy documents and request clarification on any important limitation. For long-term stays, the policy’s renewal provisions deserve as much attention as the initial premium.
Smart Insurance Reviews provides general insurance education to help consumers understand coverage and make better-informed comparisons. Learn more about our purpose and editorial approach on our About Us page.
Disclaimer: This article provides general insurance education, not personalized insurance, legal, tax, or financial advice. Policy benefits, exclusions, eligibility requirements, and premiums vary by insurer and contract. Verify current terms with the insurer and consult an appropriately qualified professional about your specific circumstances.
Sources
Frequently Asked Questions
How long can I stay abroad before I need international health insurance?
There is no universal three-month rule that determines when international health insurance becomes necessary. The appropriate coverage depends on your existing insurance, trip purpose, destination, policy duration, and need for routine or ongoing care. Check the travel policy’s duration and eligibility rules before deciding whether it is sufficient.
Does international health insurance cover pre-existing conditions?
It depends on the policy and underwriting decision. Some conditions may be excluded, while others may be accepted under specified terms. Disclose your medical history accurately and obtain written confirmation of how relevant conditions and treatments are handled.
Can I use international health insurance in more than one country?
Some plans cover multiple countries or regions, but geographical restrictions apply. Moving to another country may affect eligibility, pricing, or coverage. Inform the insurer about a planned relocation and confirm the applicable terms before moving.
Is international health insurance available for retirees and families?
Some plans accommodate retirees, spouses, and dependent children, but eligibility and benefits vary. Check age limits, dependent rules, prescription coverage, maternity provisions, and renewal conditions before selecting a policy.
Should I choose the cheapest international health insurance plan?
Not necessarily. Compare premiums alongside deductibles, benefit limits, exclusions, geographical coverage, and claims requirements. A less expensive plan may be appropriate if it meets your needs, but a low premium alone does not establish that it offers suitable protection.