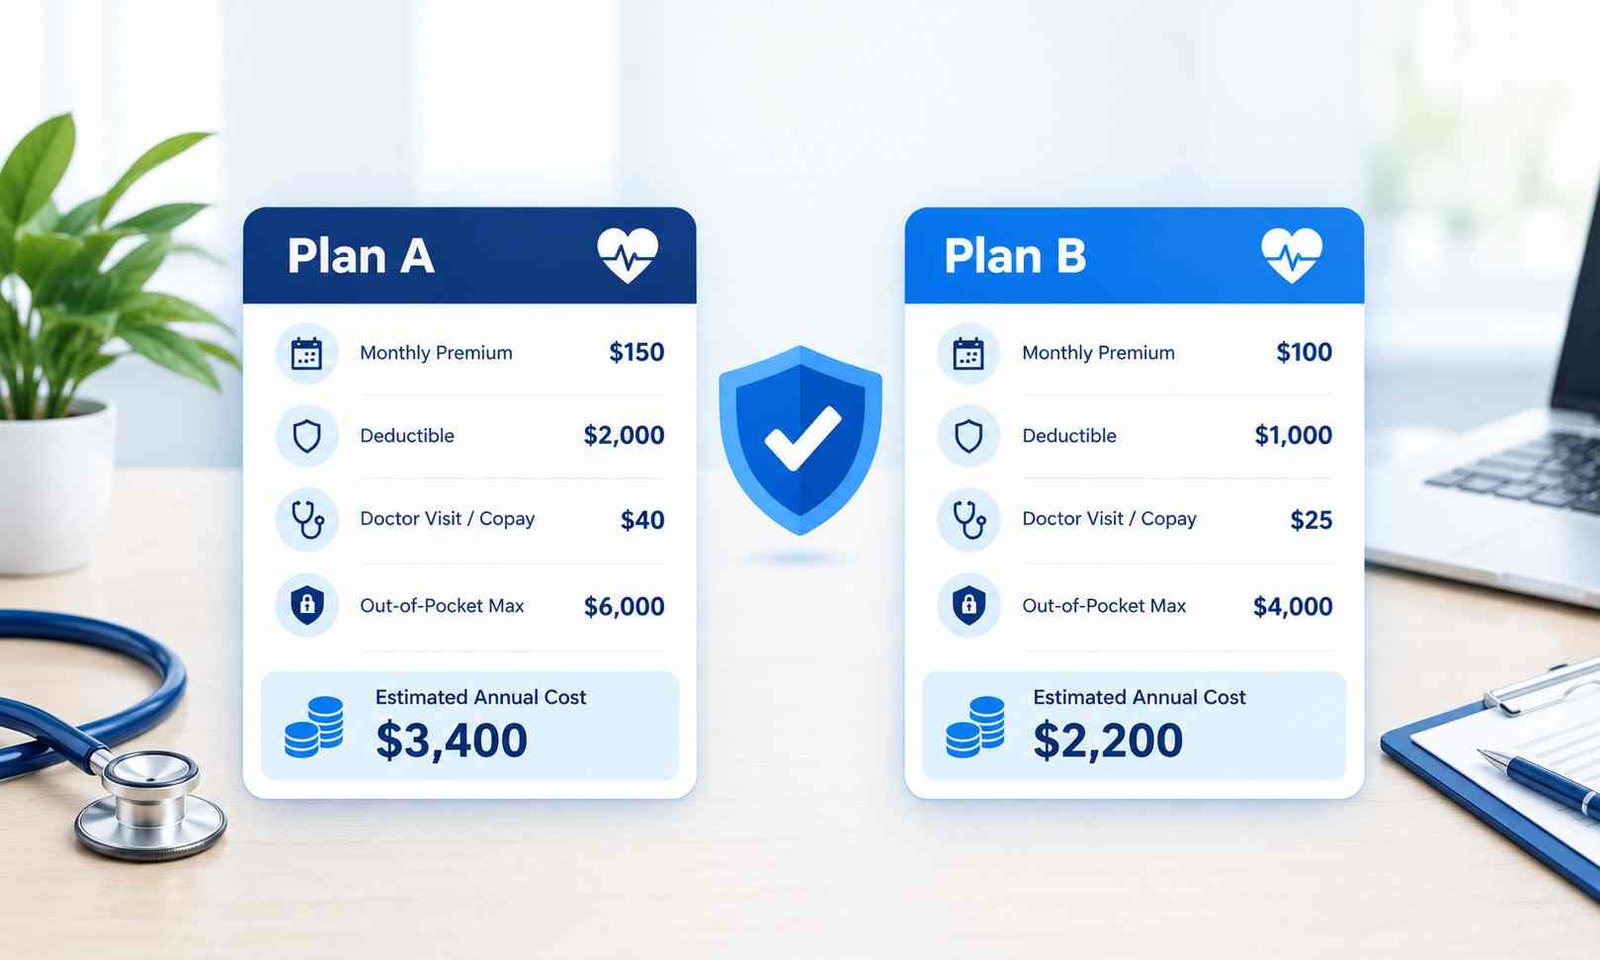
Choosing health insurance based only on the monthly premium can make it harder to understand what coverage will actually cost throughout the year. A low-premium plan may have a high deductible, while a higher-premium plan may offer lower copays or coinsurance when you need medical care.
The better approach is to compare total estimated annual health insurance costs, including premiums, deductibles, copayments, coinsurance, prescription expenses, and the plan’s out-of-pocket maximum.
The right plan depends on your budget, expected healthcare needs, preferred doctors, prescriptions, and eligibility for financial assistance. There is no single plan type that costs the least for everyone.
This guide explains how to compare health insurance costs, understand the differences between Bronze, Silver, and Gold plans, calculate expected yearly expenses, and identify easy-to-overlook costs before enrollment.
How Much Does Health Insurance Really Cost?
Health insurance costs vary by age, location, household circumstances, coverage type, plan benefits, and eligibility for financial assistance. A national average alone cannot tell you what a particular plan will cost or how much you may spend on healthcare.
Your total annual expense generally has two main parts:
- Annual premiums: Your monthly insurance payment multiplied by 12, using the amount you expect to pay after any applicable premium tax credit.
- Estimated healthcare expenses: Your share of covered medical services and prescriptions, calculated according to the plan’s deductible, copayments, coinsurance, and other benefit rules.
For someone who rarely needs medical care, a plan with lower premiums may be less expensive overall. Someone who regularly visits specialists, takes prescription medications, or expects surgery may find that a plan with higher premiums but lower cost-sharing provides better financial value.
The key is to compare plans based on the same expected healthcare needs rather than choosing the plan with the lowest monthly payment.
Understanding the Main Health Insurance Costs
Before comparing health insurance plans, understand what each cost means and how it affects your budget.
Monthly Premium
The premium is the amount you pay to maintain your health insurance coverage. It is usually charged monthly, whether or not you visit a doctor.
A lower premium can make a plan easier to fit into your monthly budget. However, the premium does not tell you how much you will pay when you receive medical care. To understand why your monthly payments may change from one year to the next, read our guide to Health insurance premium changes in 2026.
When reviewing Marketplace coverage, distinguish the full premium from the amount you expect to pay after any premium tax credit. Your eligibility for financial assistance can affect your actual cost.
Health Insurance Deductible
A deductible is the amount you must pay for certain covered healthcare services before your plan begins paying its share. Some services, including many covered preventive services, may be available before you meet the deductible.
For example, suppose a plan has a $2,000 deductible. You generally pay the applicable costs for services subject to that deductible until you have accumulated $2,000 in qualifying payments. Afterward, your plan’s copayments or coinsurance rules apply.
Not every service necessarily follows the same deductible rules. Some plans cover certain office visits, tests, or prescriptions with a fixed copayment before the deductible is met.
Read the plan’s Summary of Benefits and Coverage (SBC) to understand which services are subject to the deductible.
Copayments and Coinsurance
A copayment, or copay, is a fixed amount you pay for a covered service. Your plan might charge a set amount for a primary care appointment or a prescription.
Coinsurance is your percentage of the cost for a covered service. For example, if a service has an insurance-approved allowed amount of $500 and you owe 20% coinsurance after meeting your deductible, your share would be $100.
The allowed amount matters because coinsurance is generally calculated using the plan’s allowed amount for a covered service, not necessarily the provider’s original billed charge.
These costs can vary by service, provider network, and benefit category. Check the details for specialist appointments, laboratory tests, imaging, urgent care, emergency services, hospital stays, and prescription drugs.
Out-of-Pocket Maximum
Your out-of-pocket maximum is the most you must pay during the plan year for qualifying covered healthcare expenses included under the plan’s limit.
For covered in-network benefits, qualifying payments toward the deductible, copayments, and coinsurance generally count toward this maximum. Once you reach the limit, the plan generally pays 100% of covered in-network benefits for the rest of the plan year.
Your monthly premiums do not count toward the out-of-pocket maximum. Neither do all uncovered services or every out-of-network expense.
For Marketplace plans, HealthCare.gov lists the following federal maximum limits:
| Plan year | Individual maximum | Family maximum |
| 2026 | $10,600 | $21,200 |
| 2027 | $12,000 | $24,000 |
These are federal limits, not recommended spending targets or the actual limit for every individual plan. Some 2027 Bronze plans may qualify for a specific higher-limit exception, so review the plan documents rather than assuming the standard maximum applies to every plan.
Check the Official Marketplace out-of-pocket maximum guidance and the specific plan’s SBC before enrolling.
How to Calculate Your Real Annual Health Insurance Costs
The most useful health insurance cost comparison estimates how much you will pay for coverage and the healthcare you expect to receive.
Use this formula:
Estimated annual health insurance cost = Annual premiums + Estimated cost-sharing for expected covered care
Annual premiums are your monthly premium multiplied by 12. Estimated cost-sharing includes your expected share of covered medical services and prescriptions, calculated under the plan’s actual benefit rules.
Do not automatically add the full deductible to every copayment, coinsurance charge, and prescription expense as if each were a separate bill. Some payments count toward the deductible, some services have different rules, and qualifying payments may also count toward the out-of-pocket maximum.
Step 1: Calculate annual premiums
Multiply the monthly premium you expect to pay by 12. If you qualify for a premium tax credit, use the applicable reduced premium when estimating your payments, and account for any potential tax-credit reconciliation if your final eligibility differs from your estimate.
Step 2: Estimate your healthcare needs
Review your previous Explanation of Benefits (EOB) statements, medical bills, prescription costs, and appointment history. Consider likely specialist visits, laboratory tests, physical therapy, planned procedures, and recurring medications.
Your previous year can provide a starting point, but it does not guarantee what you will need next year.
Step 3: Apply each plan’s cost-sharing rules
Use each plan’s deductible, copayments, coinsurance, prescription benefits, network rules, and coverage limitations to estimate your share of those services.
The official HealthCare.gov guide to total healthcare costs explains how to compare estimated yearly spending rather than premiums alone.
Step 4: Compare expected and worst-case expenses
Estimate what you might pay under low, moderate, and high healthcare-use scenarios. Also consider whether you could afford the plan’s maximum potential cost exposure for covered in-network care if you experienced a serious illness or injury.
The goal is to find coverage that balances likely annual spending with protection against unexpected medical expenses.
An Illustrative Health Insurance Cost Comparison
The following example uses hypothetical figures to demonstrate how premiums and healthcare expenses affect total cost. These amounts are not market averages, real plan quotes, or predictions of what a particular enrollee will pay.
| Cost | Hypothetical Plan A | Hypothetical Plan B |
| Monthly premium | $350 | $450 |
| Annual premiums | $4,200 | $5,400 |
| Estimated annual cost-sharing for expected care | $2,400 | $1,100 |
| Estimated total annual cost | $6,600 | $6,500 |
Plan A has the lower monthly premium, but Plan B has the lower estimated annual cost in this example because its assumed cost-sharing is lower.
Your actual comparison could produce a different result. You need real premiums, benefit details, and a reasonable estimate of your healthcare needs before deciding which plan is more affordable.
Bronze vs. Silver vs. Gold Health Insurance Plans
Marketplace health insurance plans use metal categories to describe how costs are generally shared between the insurer and the enrollee for covered services. These categories do not measure the overall quality of medical care.
| Plan category | General cost-sharing pattern | When to consider it |
| Bronze | Usually lower premiums and higher costs when receiving care | When keeping monthly payments down is important and you can manage higher potential expenses |
| Silver | Usually moderate premiums and cost-sharing | When you want a balance between premium payments and healthcare expenses, especially if eligible for extra savings |
| Gold | Usually higher premiums and lower costs when receiving covered care | When you expect to use healthcare regularly and the plan’s benefits fit your needs |
| Platinum | Generally higher premiums and lower cost-sharing | When available and the plan’s combination of premiums and benefits suits your circumstances |
For Marketplace plans, the standard actuarial values are approximately 60% for Bronze, 70% for Silver, 80% for Gold, and 90% for Platinum. These percentages describe the expected share of covered costs paid by plans across a standard population. They do not mean that a particular insurer will pay the same percentage of every enrollee’s bills.
Actual deductibles, copays, drug costs, provider networks, and out-of-pocket maximums vary between plans within the same category.
When a Bronze Plan May Make Sense
Bronze coverage may be worth comparing if you want lower monthly premiums and expect relatively little healthcare use. However, consider whether you could afford the deductible and other cost-sharing if an unexpected medical need arises.
Do not assume that a Bronze plan will always have the lowest total annual cost. Premiums, covered services, and plan-specific restrictions matter.
When a Silver Plan May Be Worth a Closer Look
Silver plans deserve particular attention if you qualify for cost-sharing reductions.
These additional savings can reduce deductibles, copayments, coinsurance, and the out-of-pocket maximum. You must choose an eligible Silver Marketplace plan to receive cost-sharing reductions. Premium tax credits, when available, can apply to plans in different metal categories.
Check your eligibility and compare the actual benefits through HealthCare.gov’s cost-sharing reduction guidance.
When a Gold Plan May Be Worth Considering
Gold plans can be worth comparing if you expect recurring specialist visits, ongoing prescriptions, or other covered services that create substantial cost-sharing under a lower-premium plan.
A higher premium may be offset by lower healthcare expenses, but that result depends on the specific plan and how much care you receive.
Compare the total projected cost rather than assuming Gold coverage will always save money for people who use healthcare frequently.
Factors That Can Change Your Health Insurance Costs
Two plans with similar premiums can produce different annual expenses because they cover services and share costs differently.
Provider Networks: HMO vs. PPO
An HMO may require you to use its network and follow referral rules for certain care, subject to plan exceptions. A PPO generally offers more flexibility to receive out-of-network care, but out-of-network services can cost more and may be subject to separate rules.
Check whether your preferred doctors, hospitals, specialists, and facilities are in the network. Do not rely only on a provider’s statement that they accept a particular insurer; confirm participation in the specific plan.
Your access to doctors can matter as much as the monthly premium when estimating total healthcare costs.
Prescription Drug Formularies
A formulary lists the prescription drugs a plan covers and the rules that apply to them. Medications can be assigned to different cost tiers, which affect your copayment or coinsurance.
Before selecting a plan, check the coverage and cost-sharing for your current medications, including generic alternatives, preferred pharmacies, specialty drugs, and any prior authorization or step-therapy requirements.
A medication covered at a reasonable cost by one plan may have different restrictions or expenses under another.
Individual vs. Family Deductibles
Family health plans may have individual deductibles, family deductibles, or a combination of both.
With an embedded deductible, an individual family member may begin receiving certain plan benefits after meeting their own deductible, even if the family deductible has not been reached. With an aggregate deductible, the family may need to meet the full family deductible before the plan begins paying for services subject to that deductible for family members.
Exact rules depend on the policy. If multiple family members expect to need care, compare both the individual and family amounts.
Preventive Care and Diagnostic Services
Many recommended preventive services are covered without cost-sharing when received from an in-network provider under applicable coverage rules. However, a diagnostic test or follow-up service is not necessarily free simply because it occurs during a preventive appointment.
Confirm how your plan handles screening services, diagnostic testing, and follow-up treatment before estimating your expenses.
Prior Authorization and Coverage Restrictions
Some plans require prior authorization for certain tests, treatments, medications, or procedures. Approval requirements, exclusions, and medical-necessity rules can affect whether the plan pays for a service.
Prior authorization is not a guarantee of payment. Follow the plan’s procedures and confirm coverage when planning expensive care.
Out-of-Network Charges and Balance Billing
Out-of-network care can expose you to higher costs, and some out-of-network expenses may not count toward the plan’s in-network out-of-pocket maximum.
The federal No Surprises Act protects consumers against certain surprise medical bills, including many emergency services and specified services received at in-network facilities. It does not eliminate every possible out-of-network bill, and ground ambulance services generally are not covered by its federal protections.
Read the plan’s network rules and consult the Centers for Medicare & Medicaid Services’ No Surprises Act information if you receive an unexpected bill.
How to Lower Health Insurance Costs Without Choosing Poor-Fit Coverage
Reducing health insurance costs is not always about choosing the lowest premium. The better approach is to identify savings opportunities while keeping the benefits, doctors, and medications you need.
Check Your Eligibility for Financial Assistance
Marketplace premium tax credits may reduce monthly premiums for eligible households. Eligibility depends on household circumstances, income, and applicable rules.
For 2026, HealthCare.gov states that the additional premium savings available under temporary pandemic-era rules ended on December 31, 2025. Do not assume that your financial assistance or net premium will remain the same as in a previous year.
Update your Marketplace application when your income or household circumstances change. If you receive advance premium tax credits, your final eligibility is reconciled through your federal tax return.
Start with the official HealthCare.gov premium tax credit guidance.
Compare Silver Plans if You Qualify for Cost-Sharing Reductions
Eligible Marketplace applicants can receive extra savings on deductibles, copayments, and coinsurance by enrolling in a qualifying Silver plan.
Compare the actual Silver options available to you before assuming that a Bronze plan is cheaper overall.
Review Your Doctors and Prescriptions Before Enrolling
Confirm that your preferred providers are in-network and that your medications are covered under acceptable terms.
If you expect to need care from a particular specialist or hospital, verify those details before focusing on small differences in monthly premiums.
Consider HSA Eligibility Carefully
A Health Savings Account (HSA) can help eligible people set aside tax-advantaged funds for qualified medical expenses. HealthCare.gov identifies Bronze and Catastrophic Marketplace plans as HSA-compatible and notes that some plans in other categories may also qualify.
Check the plan’s HSA eligibility and current IRS requirements before making contributions. An HSA does not eliminate your deductible or make an otherwise unsuitable insurance plan the right choice.
Choose a Deductible You Can Realistically Afford
A plan can look affordable on a monthly basis but be difficult to manage when you need care. Consider how you would pay for a deductible, an unexpected hospital visit, or recurring prescriptions.
Your choice should account for both your expected total expenses and your ability to handle a larger bill.
A Health Insurance Comparison Checklist Before You Enroll
Use this checklist when reviewing plans for the coming year.
- Compare the net monthly premium and annual premium for each plan.
- Review individual and family deductibles.
- Check copayments and coinsurance for primary care, specialists, tests, emergency care, and hospital stays.
- Record each plan’s out-of-pocket maximum and confirm which expenses count toward it.
- Check your preferred doctors, hospitals, and other providers in the plan’s network.
- Review prescription coverage, medication tiers, pharmacy restrictions, and prior authorization requirements.
- Compare expected annual costs using the same low-, moderate-, and high-use assumptions.
- Check eligibility for premium tax credits, cost-sharing reductions, Medicaid, or other assistance where applicable.
- Read the Summary of Benefits and Coverage for exclusions, referral rules, and other conditions.
- Consider whether you could afford the plan’s potential costs if you needed substantially more care than expected.
If you receive coverage through an employer, also review your payroll contributions and any employer contribution to the premium. When comparing employer-sponsored coverage with Marketplace plans, compare the costs and benefits you would actually receive rather than assuming one type of coverage is always cheaper.
Final Thoughts: Compare Total Costs, Not Just Premiums
The best health insurance choice depends on your expected healthcare needs, financial circumstances, provider preferences, and the details of each available plan.
Start by calculating annual premiums, then estimate your share of covered medical services and prescriptions. Compare deductibles, copayments, coinsurance, network rules, prescription formularies, and out-of-pocket maximums. If you qualify for financial assistance, include it in your comparison.
Before choosing a plan, review the actual benefits and costs for the coverage year you are considering. You can compare Marketplace options and check financial assistance through HealthCare.gov.
Smart Insurance Reviews provides independent educational content to help consumers understand coverage and compare insurance costs. Use this guide as a starting point, then verify the details for your own circumstances using official Marketplace information and the plan documents.
Frequently Asked Questions
Does the monthly health insurance premium count toward the out-of-pocket maximum?
No. Premiums are separate payments for maintaining coverage and do not count toward the out-of-pocket maximum. The maximum generally applies to qualifying expenses for covered healthcare services, subject to the plan’s rules.
What counts toward a health insurance out-of-pocket maximum?
Qualifying deductibles, copayments, and coinsurance for covered services generally count toward the applicable limit. Monthly premiums, uncovered services, and certain out-of-network expenses do not. Check your plan documents for the exact rules.
Is a Bronze health insurance plan always cheaper than a Silver or Gold plan?
No. Bronze plans often have lower premiums, but their deductibles and other cost-sharing can be higher. A Silver or Gold plan could have a lower estimated annual cost for someone who expects to use more healthcare. Eligible cost-sharing reductions can also make certain Silver plans more attractive.
Can I receive financial assistance to lower health insurance costs?
Possibly. Eligible Marketplace applicants may receive premium tax credits, and some may qualify for cost-sharing reductions on Silver plans. Eligibility depends on household circumstances, income, and applicable rules. Check your current eligibility through the official Marketplace rather than relying on an old estimate.
Are preventive healthcare services always free with health insurance?
No. Many recommended preventive services are covered without cost-sharing when received in-network under applicable coverage rules. Diagnostic tests, follow-up visits, and treatment may have separate costs depending on the service and plan terms.
How can I estimate health insurance costs if my medical needs change each year?
Review your previous medical expenses, prescriptions, and Explanation of Benefits statements, then account for anticipated changes such as new medications, specialist visits, or planned procedures. Compare low-, moderate-, and high-use scenarios across plans. These estimates help with planning but cannot predict every future medical expense.
Does an out-of-pocket maximum protect me from every medical bill?
No. It generally limits qualifying cost-sharing for covered services under the plan’s rules. It does not include premiums, and uncovered services, some out-of-network expenses, and certain balance-billed charges may fall outside the limit. Review the policy terms and applicable consumer protections before relying on the maximum as a complete limit on your healthcare spending.
Educational Disclaimer
This article is for general educational purposes only and is not personalized insurance, medical, tax, or legal advice. Health insurance costs, benefits, eligibility rules, and coverage protections vary by plan, state, household circumstances, and coverage year. Verify current requirements with HealthCare.gov, your state Marketplace, the insurer’s plan documents, or an appropriately qualified professional.