Choosing a Medicare Advantage plan for 2027 should not come down to finding the plan with the lowest monthly premium.
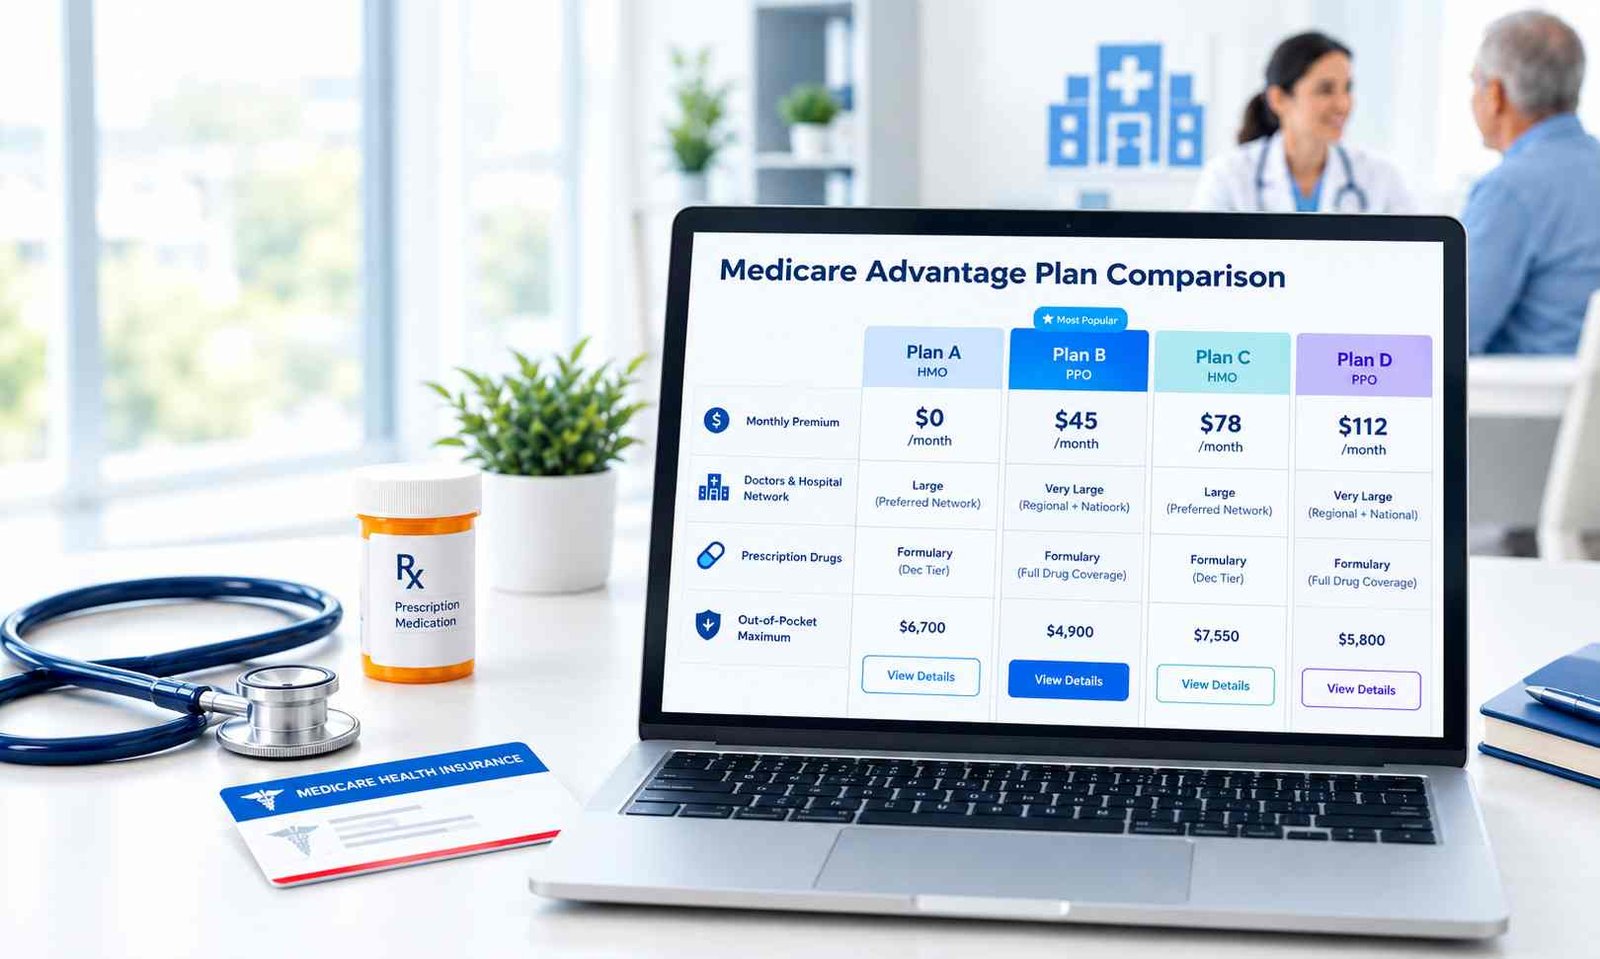
A better comparison looks at the total cost, doctors and hospitals, prescription drugs, pharmacy network, out-of-pocket maximum, plan type, prior authorization rules, supplemental benefits, and quality rating. Medicare.gov lets you enter your ZIP code to see available plans and can use your saved drugs and pharmacies to help estimate plan costs.
This guide explains how to compare Medicare Advantage plans for 2027 step by step so you can build a shortlist based on your own healthcare needs instead of choosing from a headline price or advertised benefit.
Important: Medicare Advantage plans, premiums, provider networks, formularies, benefits, and cost sharing vary by plan and location. This article provides general Medicare education and is not individualized insurance, legal, or financial advice. Review your specific plan documents and Medicare.gov before making a coverage decision.
How to Compare Medicare Advantage Plans for 2027
The most useful approach is to compare plans in this order:
- Confirm which plans are available in your ZIP code.
- Compare the total yearly cost, not just the premium.
- Check your doctors, specialists, hospitals, and other providers.
- Compare HMO, PPO, and other plan rules.
- Check every prescription against the formulary.
- Compare drug tiers and pharmacy networks.
- Review deductibles, copays, coinsurance, and the medical out-of-pocket maximum.
- Examine prior authorization and other utilization rules.
- Compare supplemental benefits and their limits.
- Review 2027 Star Ratings and official plan documents.
- Narrow the list to the plans that fit your priorities.
- Confirm the final details before enrolling.
That process matters because Medicare Advantage plans can have very different costs and rules even when they are available in the same area. Medicare.gov notes that plan premiums and other costs vary by plan, while the annual out-of-pocket limit also varies by plan.
What Is Different About Comparing Medicare Advantage Plans in 2027?
The 2027 plan year has several confirmed federal changes, but many of the numbers consumers care about most remain plan-specific.
CMS projects the weighted-average monthly Medicare Advantage premium across all MA plans at $12.00 for 2027, down from $14.37 in 2026. That is a national weighted average, not a promise that your particular plan will cost $12 per month. CMS also expects plan availability to remain broad nationally, but what is available to you depends on your location and the plans serving your area.
Prescription drug coverage also has important 2027 parameters. Under the defined standard Part D benefit, the deductible is $700, and the annual out-of-pocket threshold is $2,400 for 2027. These are standard Part D parameters and should not be confused with the medical out-of-pocket maximum for your individual Medicare Advantage plan.
That distinction is one of the most important things to understand when comparing Medicare Advantage plans for 2027.
1. Start With Medicare Advantage Plans by ZIP Code
Your first step should be finding out which plans are actually available where you live.
Medicare.gov’s Plan Compare tool asks for your ZIP code and uses it to find plans in your area. The tool also supports entering prescription drugs and pharmacies to provide more useful cost estimates.
This is important because Medicare Advantage is local. Two people living in different counties can face very different plan choices, premiums, provider networks, formularies, and supplemental benefits.
Start your comparison with:
- Your ZIP code
- The plan year: 2027
- Your current Medicare coverage
- The prescriptions you regularly take
- The pharmacies you prefer
Do not decide on a national list of “best” Medicare Advantage plans without checking whether a plan serves your area.
You can use the official Medicare Plan Compare tool here:
Medicare.gov Plan Compare for 2027
2. Compare Total Annual Cost, Not Just the Monthly Premium
A $0 Medicare Advantage premium can look attractive, but it does not necessarily mean that the plan will cost you less during the year.
Medicare Advantage costs can include:
- Monthly plan premium
- Medicare Part B premium
- Deductible
- Primary-care copays
- Specialist copays
- Hospital cost sharing
- Outpatient costs
- Prescription drug costs
- Other coinsurance or copayments
- Annual medical out-of-pocket maximum
Medicare.gov states that Medicare Advantage premiums and other costs vary by plan, and you generally continue paying your Part B premium while enrolled in Medicare Advantage.
A simple way to estimate your yearly cost
Suppose two hypothetical plans look like this:
| Cost factor | Plan A | Plan B |
| Monthly plan premium | $0 | $30 |
| Specialist visits | Lower | Higher |
| Your prescriptions | Higher cost | Lower cost |
| Preferred hospital | In network | Out of network |
| Medical out-of-pocket limit | Higher | Lower |
Plan A may appear cheaper because there is no additional monthly premium.
But if you regularly see specialists and take several prescriptions, Plan B could have the lower overall cost for your particular situation.
This is only an illustration, not a comparison of actual 2027 plans.
The lesson: Compare what you are likely to pay for the healthcare you actually use.
3. Check Your Doctors, Specialists, and Hospitals
Your provider network can be more important than a small difference in monthly premiums.
Before choosing a plan, check your:
- Primary-care doctor
- Specialists
- Preferred hospital
- Medical group
- Outpatient facilities
- Important clinics
- Other providers you regularly use
Medicare.gov explains that Medicare Advantage plans can have provider networks. HMO plans generally require members to use network providers except for certain circumstances, while PPO plans generally allow out-of-network care but may charge more.
Do not rely on an old provider directory
A doctor who accepted your 2026 plan is not automatically guaranteed to participate in your 2027 plan.
Verify the specific 2027 plan, not just the insurance company’s name.
This matters especially when your care is concentrated around a particular specialist or hospital.
A plan with a slightly higher premium may make more sense if it keeps your preferred doctors and hospital in network.
4. Compare Medicare Advantage HMO vs. PPO
The plan type can affect how easily you access care and what you pay for out-of-network services.
HMO
A Medicare Advantage HMO generally uses a defined provider network. You will usually need to use network doctors and facilities for covered care, except in certain situations such as emergencies.
Some HMO plans may also require a primary-care doctor and referrals to specialists.
An HMO may be worth considering when your preferred doctors and facilities are comfortably inside the network, and you are comfortable following the plan’s care rules.
PPO
A Medicare Advantage PPO also has a provider network, but generally allows out-of-network care for covered services at a higher cost.
PPO plans can therefore be attractive to people who value additional provider flexibility, but the higher out-of-network cost sharing can still be significant.
What should you compare?
Do not stop at the words HMO and PPO.
Check:
- In-network costs
- Out-of-network costs
- Referral requirements
- Primary-care requirements
- Specialist access
- Your actual providers
- Hospital network
- Service area
The best plan type depends on how you use healthcare.
5. Check Your Prescription Drugs Before Choosing a Plan
Prescription coverage can completely change which Medicare Advantage plan makes sense.
Most Medicare Advantage plans include Part D prescription drug coverage, but each plan has its own drug coverage rules.
A formulary is the plan’s list of covered prescription drugs. Medicare.gov explains that each plan has its own formulary.
Before choosing a plan, enter your regular medications and check:
- Drug name
- Exact strength or dosage
- Whether the drug is covered
- Formulary tier
- Copayment
- Coinsurance
- Prior authorization
- Quantity limits
- Step therapy
- Pharmacy requirements
Do not assume that two plans cover the same drug in the same way.
A medication could be covered under both plans but cost substantially different amounts because of its tier, pharmacy rules, or cost sharing.
Why your actual drug list matters
Imagine that Plan A has a lower premium, but two of your regular medications are placed on higher-cost tiers.
Plan B may have a higher monthly premium but lower cost sharing for those same medications.
For someone who takes several prescriptions, the second plan could be the more economical choice over the full year.
Medicare.gov recommends adding the prescription drugs you regularly take when comparing plans to get a more useful monthly and yearly cost estimate.
6. Compare Drug Tiers and Pharmacy Networks
Checking whether a drug is covered is only the beginning.
You should also check where you can fill the prescription and how the pharmacy affects your cost.
Medicare plans can have in-network pharmacies, preferred in-network pharmacies, and mail-order options. A preferred in-network pharmacy may offer lower out-of-pocket costs under the plan.
For each important medication, ask:
Is it covered?
Which tier is it on?
What do I pay?
Which pharmacies offer the plan’s preferred pricing?
Does my usual pharmacy participate?
A plan with excellent drug coverage at your preferred pharmacy may be more useful than one with a slightly cheaper premium but less favorable pharmacy access.
7. Understand the Medicare Advantage Out-of-Pocket Maximum
The term out-of-pocket maximum can be confusing because Medicare Advantage medical spending and Part D prescription spending use different rules.
Medicare Advantage plans have an annual out-of-pocket limit for covered Medicare Part A and Part B services. The specific amount varies by plan. After you reach the applicable limit for covered services, the plan generally pays 100% of covered health services for the rest of the calendar year.
The 2027 Part D out-of-pocket threshold is $2,400 under the defined standard Part D benefit. That is a prescription-drug threshold, not the medical out-of-pocket maximum for the entire Medicare Advantage plan.
Think of them as two separate questions
Medical costs:
How much could I have to pay for covered Part A and Part B services under this Medicare Advantage plan?
Prescription costs:
How does the plan’s Part D coverage handle my medications, and how will my qualifying drug spending work toward the 2027 Part D threshold?
This distinction is especially important for people who have both regular medical care and significant prescription expenses.
For a deeper look at the 2027 prescription changes, see Smart Insurance Reviews’ Medicare Part D changes in 2027 guide.
8. Check Deductibles, Copays, and Coinsurance
Do not compare a plan’s premium and out-of-pocket maximum while ignoring the costs you are most likely to encounter.
Look specifically at:
- Primary-care visits
- Specialist visits
- Urgent care
- Emergency care
- Hospital stays
- Outpatient surgery
- Diagnostic tests
- Imaging
- Durable medical equipment
- Mental health services
- Skilled nursing care
For example, two plans could both have similar premiums and annual out-of-pocket limits but charge different amounts for specialist visits or hospital care.
The plan that fits your health needs may therefore depend more on these everyday cost-sharing details than on the premium.
9. Look for Prior Authorization and Referral Rules
Cost is only part of plan comparison. Access rules matter too.
Medicare.gov notes that Medicare Advantage members will typically need prior authorization from their plan before the plan covers certain services or supplies.
Prior authorization generally means that the plan requires approval before covering a particular service, item, or drug.
This can matter when comparing plans if you regularly use services that may be subject to plan rules.
Also check whether you need a referral to see specialists.
Medicare.gov’s comparison of plan types shows that referral requirements differ by plan type, with some HMO structures generally requiring referrals while PPO plans generally do not.
So ask two separate questions:
Is my provider in network?
Will the plan require prior authorization or a referral for the care I need?
These are not the same issue.
10. Compare Medicare Advantage Supplemental Benefits Carefully
One reason people consider Medicare Advantage is the possibility of additional benefits that Original Medicare generally does not cover.
Depending on the plan, supplemental benefits may include:
- Dental services
- Vision services
- Hearing benefits
- Fitness benefits
- Transportation
- Over-the-counter benefits
- Food-related benefits
- Other supplemental services
Medicare.gov confirms that Medicare Advantage plans may offer extra benefits beyond those covered by Original Medicare, but the exact benefits depend on the plan.
Do not compare supplemental benefits only by the advertised dollar amount.
For a dental benefit, for example, check:
- What services are covered
- Preventive vs. comprehensive services
- Annual limits
- Cost sharing
- Provider network
- Eligibility requirements
- Benefit restrictions
A benefit is valuable only when its actual terms fit what you are likely to use.
Smart Insurance Reviews also has a separate guide covering Dental insurance options for seniors on Medicare.
11. Check 2027 Medicare Advantage Star Ratings
Medicare Advantage Star Ratings provide another way to evaluate plan quality.
CMS says the Star Ratings system helps beneficiaries compare the quality of Medicare Advantage and prescription drug plans. For 2027, CMS finalized changes to the measures used in the ratings system, including removing certain measures and adding a Part C depression screening and follow-up measure beginning with the 2027 measurement year, which is scheduled to affect the 2029 Star Ratings.
The important point for consumers is simple:
Do not evaluate a plan using its premium alone.
But also do not treat a Star Rating as a universal “best plan” label.
A highly rated plan can still be a poor fit if:
- Your doctor is outside its network
- Your hospital is not included
- Your medications are expensive
- The plan’s service area does not suit you
- Its cost sharing does not fit your expected healthcare use
Star Ratings are one factor in a broader Medicare Advantage plan comparison.
12. Read the ANOC, EOC, and Summary of Benefits
Your plan documents are among the most useful sources for understanding what will actually change or what the plan covers.
Annual Notice of Change (ANOC)
The Annual Notice of Change explains upcoming changes to your plan’s coverage, costs, and other details that take effect in January.
Medicare says the ANOC is sent each fall.
Use it to answer:
What is changing from 2026 to 2027?
Look for changes to:
- Premium
- Deductible
- Copays
- Out-of-pocket limit
- Provider network
- Drug formulary
- Pharmacy network
- Dental, vision, and hearing benefits
- Other supplemental benefits
Evidence of Coverage (EOC)
The Evidence of Coverage goes deeper.
It explains what the plan covers, what you pay, and the rules that apply to your coverage.
A useful approach is:
Use the ANOC to find the changes.
Use the EOC to investigate the details.
Then use the Summary of Benefits and the Medicare Plan Compare tool to help verify the important numbers.
A Simple Side-by-Side Medicare Advantage Comparison Method
Once you have several 2027 plans, narrow them down using the same questions for each plan.
| What to compare | Question to ask |
| Premium | What will I pay each month? |
| Medical costs | What will my common doctor, specialist, hospital, and outpatient services cost? |
| Deductible | What do I pay before certain coverage begins? |
| Medical out-of-pocket limit | What is the plan’s annual limit for covered Part A and Part B services? |
| Providers | Are my doctors and preferred hospital in network? |
| Plan type | Is it an HMO, PPO, or another plan type? |
| Referrals | Do I need referrals for specialists? |
| Prior authorization | Are services, drugs, or supplies subject to approval requirements? |
| Prescriptions | Are all my medications covered? |
| Drug tiers | What tier is each important medication on? |
| Pharmacy | Is my preferred pharmacy in network or preferred? |
| Supplemental benefits | Which benefits will I realistically use? |
| Star Rating | How does the plan’s quality rating compare? |
| Documents | Have I reviewed the ANOC, EOC, and Summary of Benefits? |
You do not need the plan with the best score in every category.
You need the plan whose trade-offs make the most sense for your circumstances.
Who Should Pay Extra Attention to Each Comparison Factor?
Different healthcare situations make different plan features more important.
If you see doctors frequently
Prioritize provider networks, specialist copays, referrals, prior authorization, and the medical out-of-pocket limit.
If you take several prescriptions
Prioritize the formulary, drug tiers, pharmacy network, utilization rules, and estimated annual drug costs.
If you rarely use healthcare
You may place more weight on the monthly premium and basic access while still checking the out-of-pocket maximum and network.
If you travel or spend time in another state
Pay close attention to the plan’s service area, network structure, and out-of-network rules. Medicare Advantage plans do not all handle routine out-of-area care in the same way.
If dental, vision, or hearing coverage is important
Compare the actual benefit limits and provider requirements rather than choosing a plan simply because it advertises an extra benefit.
Common Medicare Advantage Comparison Mistakes
Choosing the lowest premium
A low premium can be appealing, but higher copays, drug costs, or limited networks can make another plan a better fit.
Checking only whether a drug is covered
A covered drug can still have an unfavorable tier, pharmacy requirement, or utilization restriction.
Assuming your doctor is still in network
Always verify the specific 2027 plan.
Comparing only the out-of-pocket maximum
The maximum tells you about financial protection, but it does not tell you what you are likely to spend during a normal year.
Ignoring the pharmacy network
The pharmacy you already use may not offer the same cost under every plan.
Treating extra benefits as guaranteed value
A $1,000 dental or food benefit headline means little unless you meet the eligibility requirements and can actually use the benefit for services or products you need.
Waiting until the last few days to compare
A rushed comparison makes it easier to overlook provider, drug, or document changes.
When Should You Compare Medicare Advantage Plans for 2027?
For people choosing coverage for 2027 during the regular Medicare Open Enrollment Period, the key window is October 15 through December 7, 2026. Changes made during this period generally take effect January 1, 2027.
People who are already enrolled in Medicare Advantage have another opportunity during the Medicare Advantage Open Enrollment Period from January 1 through March 31, 2027. During this period, eligible beneficiaries can generally make one permitted change, such as switching to another Medicare Advantage plan or returning to Original Medicare.
For more detail about the 2027 enrollment periods and switching rules, see Smart Insurance Reviews’ Medicare Advantage Open Enrollment 2027 guide.
The important point is to compare before the deadline, rather than waiting to discover a network or prescription problem after the new year begins.
What Is the Best Way to Compare Medicare Advantage Plans Side by Side?
Start with three pieces of information:
Your ZIP code
Your medication list
Your healthcare providers
Then compare each available plan using the same checklist.
First, compare the total costs.
Next, verify the network.
Then check your prescriptions and pharmacies.
After that, review the medical out-of-pocket limit, plan rules, supplemental benefits, Star Ratings, and plan documents.
Finally, look at the trade-offs.
The plan with the lowest premium may not be the plan with the lowest total cost for you. The plan with the richest extra benefits may not have your preferred hospital. And the plan with the strongest drug coverage may have provider rules you do not want.
A good Medicare Advantage plan comparison is therefore less about finding a universal winner and more about finding the best fit between your healthcare needs and the plan’s actual rules and costs.
What to Consider Before Choosing a Medicare Advantage Plan
Learning how to compare Medicare Advantage plans is really about knowing which details deserve your attention before you enroll.
For 2027, start with the plans available in your ZIP code. Then compare total costs, doctors and hospitals, HMO or PPO rules, prescriptions, drug tiers, pharmacies, medical out-of-pocket limits, prior authorization, supplemental benefits, Star Ratings, and the documents that explain the plan’s coverage.
Do not let a $0 premium or an attractive extra benefit decide for you.
Your medications, doctors, healthcare use, budget, and location should drive the comparison.
Smart Insurance Reviews provides independent insurance education to help consumers understand these decisions. Its Medicare Advantage coverage also explains the broader 2027 changes, while this guide focuses specifically on the process of comparing available plans.
For decisions involving your personal Medicare coverage, always verify the latest information through Medicare.gov and your plan’s official documents.
Frequently Asked Questions
What should I compare first when choosing a Medicare Advantage plan?
Start with your ZIP code, doctors, prescriptions, and total costs. These four areas quickly eliminate plans that may not fit your location or healthcare needs.
Is a $0 Medicare Advantage premium really free?
A $0 additional Medicare Advantage premium does not mean you have no Medicare-related costs. You generally still have to pay your Medicare Part B premium, and the plan can have deductibles, copayments, coinsurance, and other cost sharing.
Do prescription drug costs count toward the Medicare Advantage medical out-of-pocket maximum?
You should treat them separately when comparing coverage. The Medicare Advantage medical out-of-pocket limit applies to covered Part A and Part B services, while Part D has its own prescription-drug cost rules and 2027 out-of-pocket threshold.
Can my doctor be removed from a Medicare Advantage network?
Provider participation can change, so it is important to verify your doctors and hospitals against the specific plan for the upcoming plan year rather than assuming your current network will remain unchanged. Medicare.gov recommends checking whether your doctors and pharmacies are in network before choosing a plan.
Should I compare Medicare Advantage plans every year?
It is generally wise to review your current plan each year because premiums, benefits, costs, provider networks, and drug coverage can change. The Annual Notice of Change is specifically intended to explain upcoming changes for the next plan year.
What if my medication is covered but the cost is still high?
Check the drug’s formulary tier, copayment or coinsurance, preferred pharmacy options, and any utilization requirements. A drug can be covered while still having a relatively high cost under a particular plan.
Is the highest-rated Medicare Advantage plan automatically the best choice?
No. Star Ratings are useful for evaluating plan quality, but you should also consider your doctors, hospital, prescriptions, costs, provider network, plan rules, and supplemental benefits. CMS describes Star Ratings as a quality-comparison tool, not a replacement for evaluating your personal coverage needs